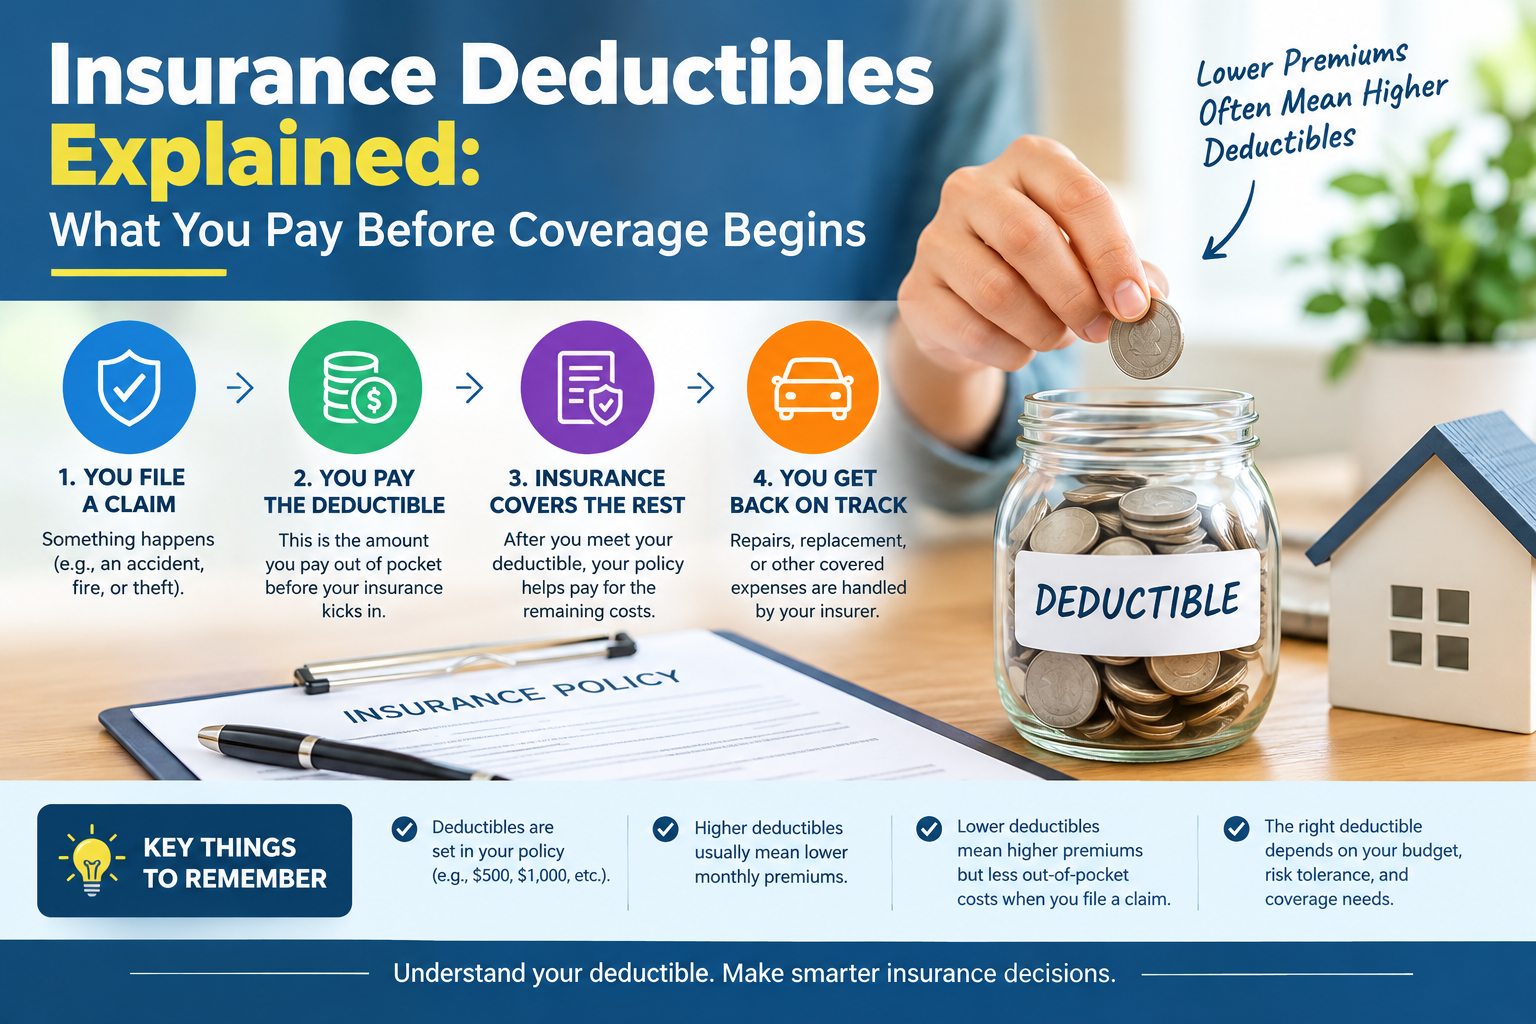
An insurance deductible is the amount a policyholder is generally responsible for paying toward a covered loss before the insurer pays its share. It determines how costs are divided when a claim is approved, but it does not mean the insurer will automatically reimburse every expense above that amount. The policy’s coverage terms, limits, exclusions, and claim assessment all affect what the insurer ultimately pays. A deductible may apply separately to different types of coverage or claims, so the relevant policy provisions matter.
A deductible is usually not a fee that the policyholder sends to the insurance company. Instead, it is commonly the portion of a covered repair or other eligible loss that the policyholder pays. For example, suppose a covered repair costs $4,000 and the applicable deductible is $1,000. The policyholder would generally pay the first $1,000, while the insurer would cover the remaining eligible $3,000, assuming the claim is approved and no other policy terms change that calculation. If the repair cost were less than the deductible, the policyholder might pay the full amount themselves.
How a deductible works depends on the insurance product and the circumstances of the loss. Some policies apply one deductible to each claim, while others may use different amounts for particular events or coverage categories. The deductible may also be a fixed dollar amount or, in some cases, calculated as a percentage of an insured value. It is therefore useful to check the declarations page and the wording for the specific coverage involved rather than rely on a general rule. Understanding the deductible can help policyholders estimate their out-of-pocket responsibility and compare insurance options, alongside premiums, coverage limits, and exclusions. Before repairs begin, they can also confirm how the insurer has calculated the covered amount and which deductible applies.
When a covered event occurs, such as a collision, storm, or burst pipe, the first step is to notify your insurer and open a claim. Provide details about what happened, when it occurred, and what was damaged or lost. Photos, receipts, repair records, and other supporting documents can help the insurer review the claim. Your policy explains reporting deadlines and any steps you must take to prevent further damage, so follow its requirements while the claim is being assessed.
The insurer then investigates the event and evaluates the loss. An adjuster may inspect the damage, request documentation, or review a repair estimate to determine which costs are eligible under the policy. The deductible is applied to covered costs, not necessarily to every amount listed on a bill. For example, if eligible repairs total $5,000 and your deductible is $1,000, the insurer generally calculates its payment on the remaining $4,000, subject to policy terms. This is the practical answer to “what is a deductible insurance” in a claim: the amount you are responsible for before the insurer contributes.
How you pay that share depends on the claim and payment arrangement. You might pay the repair provider directly, with the insurer paying the remaining approved amount, or the insurer may subtract the deductible from a settlement sent to you. In some cases, payment goes to both you and a lender or contractor. The initial estimate may also change as hidden damage is found or repairs are completed, so the final payment can differ from the first calculation. Depreciation, coverage limits, exclusions, and other policy conditions may reduce or restrict payment as well. Review the settlement explanation and ask the insurer how each figure was determined. If the loss is below the deductible, the insurer may make no payment, although reporting requirements can still apply. Confirm whether any deductible applies per claim, per item, or under a special rule for certain losses, since the details depend on your policy.
Deductibles can be structured in several ways, and the type determines how much you pay when a covered loss occurs. A fixed-dollar deductible is a set amount stated in the policy, such as $1,000. If a covered repair costs $5,000, you generally pay the deductible and the insurer pays the remaining eligible amount, subject to policy limits and exclusions. This is the familiar structure in many auto and homeowners policies. When asking what an insurance deductible is, it is useful to check not only its amount but also how the policy applies it.
A percentage deductible is calculated as a percentage of an insured value, rather than a percentage of the repair bill. In homeowners insurance, the calculation often uses the home’s insured value. For example, a 2% deductible on a home insured for $300,000 would equal $6,000. This can make the amount due substantially larger than a fixed-dollar deductible, especially after a major loss. Policies may apply percentage deductibles to specific risks, such as wind or hail, so the declarations page and policy wording should be reviewed carefully.
With a per-claim or per-occurrence deductible, the deductible applies separately to each qualifying claim or event. If separate incidents cause damage, each may trigger its own deductible, depending on the policy’s definition of an occurrence. By contrast, an annual or aggregate deductible applies across a policy period. Qualifying costs or claims may accumulate toward a specified threshold, or the policy may require the insured to meet a single annual amount before certain coverage responds. These structures are more common in some health, commercial, and specialty policies.
Names and calculations are not always consistent across insurers. A policy may define “claim,” “occurrence,” or the coverage period in a way that changes how often a deductible applies. Before choosing coverage or filing a claim, confirm the relevant deductible, what value it is based on, and whether it applies per event or across the year. The policy contract controls if a summary or quote describes the terms differently.
Deductibles work differently across insurance policies, so the amount you pay—and when you pay it—depends on the type of coverage involved. Knowing how a deductible applies can help you compare plans and estimate your share of a claim. When asking what is a deductible insurance policy, the key point is that it is typically the portion of an eligible loss you pay before the insurer contributes.
With auto insurance, collision and comprehensive coverage may each have their own deductible. Collision coverage generally applies to damage from a crash, while comprehensive coverage addresses certain non-collision events, such as theft, hail, or falling objects. If a covered claim involves one of these protections, you usually pay the relevant deductible before the insurer pays the remaining covered amount, subject to policy limits. Liability coverage is different: it commonly has no deductible for a covered claim against you for injury or damage to someone else, although policy terms vary.
Homeowners policies may use a standard deductible for many claims and separate deductibles for particular risks. A windstorm or hurricane deductible, for example, may be calculated as a percentage of the home’s insured value rather than a fixed dollar amount. Some causes of damage may be excluded altogether, so a deductible does not mean every loss is covered.
In health insurance, the deductible is generally what you pay for covered services before the plan begins sharing certain costs. However, copayments or coinsurance may apply in different ways, and many plans cover specified preventive care before the deductible is met. The out-of-pocket maximum also matters: after eligible spending reaches that limit, the plan generally pays the full allowed amount for covered services for the rest of the plan year.
Renters, travel, and other policies may also include deductibles. A renters policy might require you to pay part of a covered loss to belongings, while travel coverage may apply a deductible to eligible medical or baggage claims. Reviewing each policy’s deductible, exclusions, and cost-sharing rules clarifies how much you could owe when making a claim.
When considering what is a deductible insurance, it helps to compare it with the premium and other costs you may pay. A deductible is the amount you are responsible for paying toward eligible covered expenses before your insurer begins paying according to the policy. A premium, by contrast, is the price you pay to keep the policy active, often monthly or annually, regardless of whether you make a claim.
In many types of insurance, selecting a higher deductible can reduce the premium. You accept more financial responsibility if a covered loss occurs, and the insurer may charge less for the coverage. Choosing a lower deductible often means paying a higher premium in exchange for having the insurer’s share begin sooner. This trade-off is common, but it is not identical across every policy: pricing also reflects factors such as coverage limits, location, risk, and insurer rules. A deductible is therefore only one part of the total cost of insurance.
Other forms of cost-sharing work differently. A copayment, or copay, is usually a fixed amount paid for a covered service, such as a medical appointment. Coinsurance is a percentage of eligible costs that you pay, often after meeting the deductible. A policy limit is the maximum amount the insurer will pay for specified coverage or losses; it is not an amount you must pay before coverage begins.
For health insurance, the out-of-pocket maximum generally caps eligible cost-sharing for covered in-network care under the plan’s rules. Depending on the plan, qualifying deductibles, copayments, and coinsurance may count toward that cap. Premiums typically do not count, and some services or out-of-network expenses may be treated differently. Reaching the maximum does not replace the deductible; rather, it limits what you pay in qualifying cost-sharing for the remainder of the plan year. Review the policy’s terms to understand which expenses count and how the deductible applies.
A deductible does not automatically apply to every insurance claim. It generally matters only when the event falls within a coverage section that is triggered and the policy terms require the insured to pay a deductible. Before estimating an out-of-pocket cost, identify the type of loss, the coverage that responds, and any conditions attached to that coverage. The answer to “what is a deductible insurance policy requires?” can therefore vary even within one policy, because different coverages may have different rules.
For example, a comprehensive auto claim for hail damage or a stolen vehicle may be subject to the comprehensive coverage deductible shown in the policy. A collision claim may have a separate deductible. By contrast, auto liability coverage for damage the policyholder causes to another person’s property typically pays covered losses under different terms and does not use the policyholder’s collision or comprehensive deductible. The insurer may still investigate responsibility, apply coverage limits, and assess exclusions. If a covered repair costs less than the applicable deductible, the insurer may make no payment, leaving the policyholder to pay the repair cost.
Health insurance also uses cost-sharing rules that can make a deductible apply differently from a fixed charge or coinsurance. A covered service may be subject to the deductible, while another service may have a copayment before the deductible is met; the plan documents determine the details. Other policy provisions can affect whether or how much the deductible applies. Exclusions may mean a loss is not covered at all, while a waiting period may delay coverage. Network rules can change the eligible amount or the member’s cost, and coverage limits can cap payment even after a deductible is satisfied. Special endorsements may add, remove, or modify a deductible for particular risks. Reviewing the declarations page and the relevant coverage wording helps clarify which deductible applies, when it is owed, and what other conditions affect a claim.
Choosing a deductible is a balance between what you pay regularly for coverage and what you can manage after a covered loss. A higher deductible often lowers the premium, but the savings should be weighed against the amount you would need to pay out of pocket before insurance contributes. The right choice depends on your finances and the risks covered by the policy, not simply on which option has the lowest monthly cost.
Start by reviewing your emergency savings. Could you pay the deductible promptly without missing essential bills or relying on expensive borrowing? If not, a lower deductible may be worth the higher premium. Also consider income stability: someone with irregular earnings or limited cash reserves may need more financial flexibility than someone with steady income and substantial savings. Avoid selecting an amount that would be difficult to fund in a stressful situation.
Next, assess how likely a claim may be and how costly a loss could become. Your past claims, living situation, vehicle use, local weather risks, and the value of insured property can all inform this judgment. No estimate can predict every event, so consider both the chance of a claim and whether you could absorb the financial impact if one occurred.
Compare the actual premium difference between deductible options. If raising the deductible saves only a small amount each year, the trade-off may not justify taking on substantially more risk. Ask how long it would take for the savings to equal the additional amount you would owe in a claim, while remembering that a loss could happen at any time.
Finally, check the full policy terms. Some policies offer different deductibles for particular causes of loss, and multiple deductibles may apply to one event. Confirm which coverage limits, exclusions, and deductible rules matter for your circumstances. When considering what is a deductible insurance policyholders must pay, look beyond the headline premium: choose an amount you can comfortably cover, and compare the overall protection and costs before deciding.
To calculate your share of a covered claim, start with the insurer-approved loss amount—not necessarily the repair estimate or the total damage initially reported. For a fixed deductible, subtract the deductible from the eligible loss. If a covered loss is approved at $2,500 and the policy has a $500 deductible, the basic calculation is $2,500 minus $500, leaving a potential insurer payment of $2,000. The policyholder is responsible for the deductible, while the insurer pays the remaining covered amount, subject to the policy’s limits and terms. This simple example helps clarify what is a deductible insurance, but a real claim may involve additional adjustments.
If the approved covered loss is less than the deductible, the insurer generally does not pay toward that loss. For instance, if repairs are approved at $400 and the deductible is $500, the policyholder may pay the full $400. When the eligible loss exceeds the deductible, the insurer’s share still cannot exceed the applicable coverage limit. If a policy limit is lower than the amount remaining after the deductible, payment may be capped at that limit. Other claim-specific rules can also affect the amount ultimately reimbursed.
Some policies use a percentage deductible instead of a fixed dollar amount. To estimate it, multiply the stated percentage by the insured value specified in the policy. For example, a 2% deductible applied to a stated dwelling value of $300,000 equals $6,000. The policyholder would generally bear that amount for a qualifying claim before the insurer contributes, subject to the contract. Check how the policy defines the relevant value: it may be the insured property value, dwelling limit, or another stated figure, and it may differ from a home’s market price. Actual settlements can also be adjusted for exclusions, depreciation, coinsurance requirements, sublimits, and other policy terms. Review the declarations and wording, and ask the insurer how it calculated both the approved loss and the deductible when an estimate differs from your own.
Before buying or renewing a policy, clarify the deductible’s amount and how it is calculated. Is it a fixed dollar figure or a percentage of an insured value, such as a home’s insured amount? Does it apply separately to each claim, to each event, or once per policy year? For example, could one storm produce multiple claims or trigger a different deductible than other damage? These details affect the amount you may need to pay before the insurer contributes.
Check whether the policy has separate deductibles for different coverage types or named risks, such as wind, flood, or earthquake damage. Ask which expenses count toward the deductible and whether certain services, preventive care, or specific losses are exempt. Find out how choosing a higher or lower deductible would change your premium, and compare the possible savings with the amount you could comfortably pay after a loss. The lowest premium may not provide the most suitable balance of cost and risk.
Finally, ask whether limits, exclusions, network requirements, or an annual out-of-pocket maximum alter how the deductible is applied. In health coverage, for instance, network status and covered-service rules can affect what expenses count; in property or auto insurance, exclusions and coverage limits may restrict payment regardless of the deductible. Review the declarations page for the listed amounts, then read the full policy wording for definitions, exceptions, and calculation rules. If you are researching “what is a deductible insurance” and an example remains unclear, ask the insurer or a licensed agent to explain how the policy would handle that specific situation. Confirm the answer in writing when possible, especially if it affects your decision to buy, renew, or adjust coverage.