Understanding Home Insurance
Home insurance, also known as homeowners insurance, serves as a vital financial tool designed to protect property owners from potential losses due to damage, theft, or liability claims. The primary purpose of home insurance is to provide coverage for a residence and its contents against various risks, thereby ensuring peace of mind for homeowners.
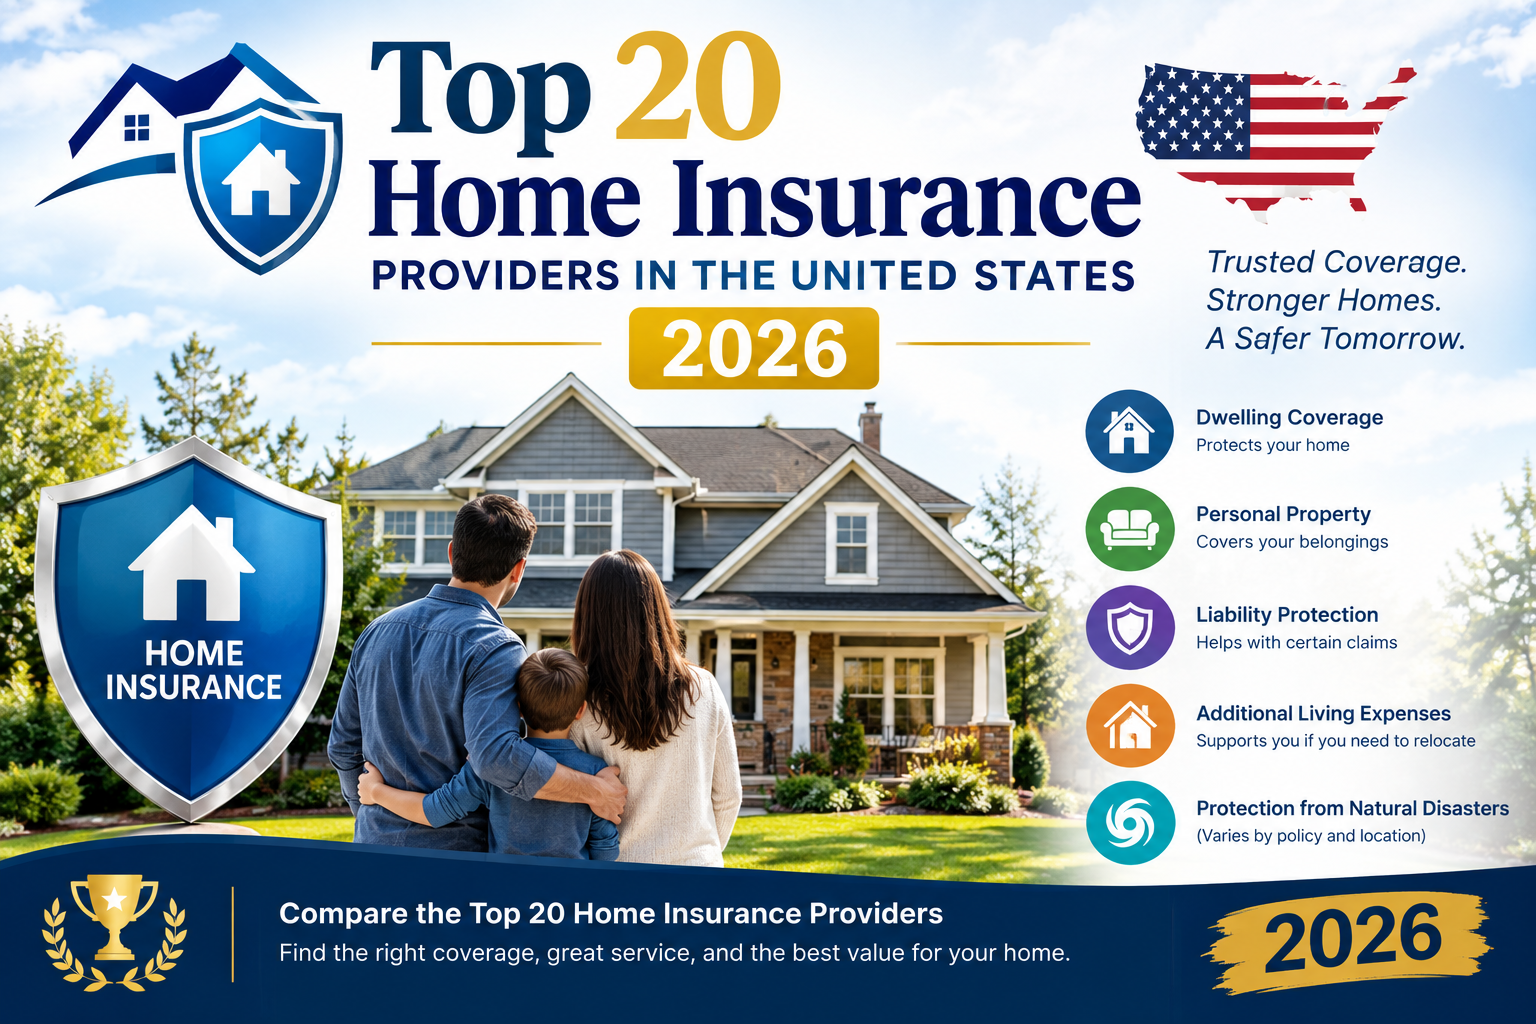
Home insurance policies can differ widely, but most standard policies include several key types of coverage. One of the main components is dwelling coverage, which protects the physical structure of the home itself, encompassing the house and any attached structures, such as garages or decks. This coverage can help homeowners recuperate their financial losses in the event of disasters like fires, storms, or vandalism.
In addition to dwelling coverage, personal property coverage is another important aspect. This type of coverage safeguards personal belongings inside the home, including furniture, electronics, and clothing, should they be damaged or lost due to covered events. Homeowners are often encouraged to create an inventory of their possessions to ensure they are adequately covered.
Liability coverage is also a crucial element of home insurance, protecting homeowners from legal claims or lawsuits arising from injuries that occur on their property. If a visitor is injured or if damage is caused to someone else’s property, liability insurance can cover legal costs and damages, providing additional protection for the policyholder.
Moreover, additional living expenses (ALE) coverage is worth mentioning. This component assists homeowners in covering the costs of temporary housing, meals, and other necessary expenses if the home becomes uninhabitable due to a covered event. This support can be integral for homeowners as they navigate unforeseen circumstances.
Understanding these basic elements of home insurance highlights its importance in safeguarding homeowners’ investments. As individuals seek options among the top 20 best home insurance companies in the United States, being aware of the fundamental aspects of coverage can facilitate informed decisions regarding protection for their homes and assets.
Factors to Consider When Choosing Home Insurance
When selecting a home insurance policy, there are several important factors that homeowners must carefully evaluate to ensure they make the right choice. Understanding the specifics of coverage limits is essential, as these limits dictate the maximum amount an insurer will pay in the event of a claim. Homeowners should assess whether the coverage limits will adequately protect their homes and personal belongings.
Another critical aspect to consider is the deductible associated with the policy. The deductible is the amount the homeowner needs to pay out-of-pocket before insurance kicks in. A lower deductible typically results in higher premium costs, while a higher deductible can reduce premium amounts, but may lead to more out-of-pocket expenses in the case of a claim.
Premium costs are a significant factor in making an informed decision. Homeowners should compare quotes from various providers to gauge what coverage is offered at different price points. However, the cheapest policy is not always the best; it is essential to balance cost with adequate coverage and reputable service.
Customer service reputation is another vital consideration. Homeowners should research reviews and ratings concerning a company’s responsiveness and professionalism in dealing with claims. A provider that fails to handle claims efficiently can lead to delays and potential financial loss.
Finally, understanding how claims are processed by the insurer is paramount. Homeowners should inquire about the claims process, including the average time taken from filing a claim to receiving compensation. A streamlined and transparent claims process signifies a provider’s reliability and can add peace of mind.
In conclusion, when evaluating the top 20 best home insurance companies in the United States, homeowners must give careful consideration to coverage limits, deductibles, premium costs, customer service reputation, and claims handling to make an informed choice.
The Role of Insurance Ratings and Reviews
When selecting a home insurance provider, one critical factor often influencing consumers’ decisions is the ratings and reviews of those companies. The top 20 best home insurance companies in the United States are frequently assessed by various independent rating agencies that provide evaluations based on multiple criteria, including customer satisfaction, financial strength, and claims handling efficiency. These ratings serve as a foundational resource for homeowners seeking reliable insurance coverage.
Prominent rating organizations, such as J.D. Power, A.M. Best, and the Better Business Bureau, have established reputations for evaluating insurance companies. J.D. Power, for instance, conducts extensive surveys that gauge customer satisfaction and experience across different insurance providers. Their annual ratings highlight which insurers excel in customer service, clearly showing the top 20 best home insurance companies in the United States identified by user feedback.
A.M. Best, on the other hand, focuses on the financial stability of insurance companies. Their ratings are particularly relevant because they indicate the insurer’s ability to pay claims, an essential factor for policyholders. When reviewing potential home insurance options, consumers should take note of these financial ratings, ensuring that they select a provider capable of meeting their future needs in times of loss.
Moreover, the Better Business Bureau provides insights regarding customer complaints and resolutions, which can impact a consumer’s choice. The overall sentiment in customer reviews on various platforms such as Trustpilot or Google Reviews can also offer valuable perspectives on the customer experience. In essence, both ratings from reputable agencies and genuine customer feedback collectively influence the standing of the top 20 best home insurance companies in the United States. Evaluating these can empower homeowners to make informed choices, ensuring they select a trustworthy provider that aligns with their insurance needs.
List of Top 20 Home Insurance Companies
Finding the right home insurance provider is crucial for homeowners seeking protection and peace of mind. Below is a comprehensive overview of the top 20 best home insurance companies in the United States, providing information on each company’s unique offerings and market positions.
1. State Farm: Known for its extensive network of agents and personalized service, State Farm offers customizable policies and discounts for bundling insurance.
2. Allstate: Allstate is recognized for its comprehensive coverage options and innovative tools such as the Allstate Mobile app, helping policyholders easily manage their policies.
3. Farmers Insurance: With a strong emphasis on customer service, Farmers provides a range of coverage options that include unique add-ons like equipment breakdown coverage.
4. Liberty Mutual: Liberty Mutual stands out for its flexible premium plans and wide range of policy discounts tailored to diverse customer needs.
5. Nationwide: Nationwide offers an array of home insurance products with specialized coverage options for unique financial lifestyles.
6. Progressive: Known for its competitive pricing and ease of use, Progressive provides a user-friendly online quoting system and various optional coverages.
7. USAA: Exclusively serving military members and their families, USAA is praised for outstanding service and highly competitive policies.
8. Travelers: Travelers offers various coverage options and a robust claims handling process, making it a reliable choice for homeowners.
9. Chubb: Chubb caters primarily to high-net-worth individuals, providing exceptional coverages tailored to unique and valuable possessions.
10. MetLife: With a 150-year reputation, MetLife offers home insurance that can be customized to fit a variety of lifestyles and budgets.
11. American Family Insurance: This company focuses on customer education, providing comprehensive coverage options and a dedication to community engagement.
12. Erie Insurance: Known for its personalized service, Erie provides competitive rates and a wide array of coverage options.
13. Safeco: A Liberty Mutual subsidiary, Safeco is known for its flexible options and customizable policies tailored to meet individual homeowner needs.
14. The Hartford: The Hartford excels in providing unique features such as home business coverage and 24/7 customer service for claims assistance.
15. AIG: AIG specializes in high-end home insurance solutions, providing comprehensive coverage for luxury homes and valuable assets.
16. Assurant: Known for its extensive risk management services, Assurant offers innovative and flexible home insurance solutions.
17. Hanover Insurance: With a focus on small businesses and homeowners, Hanover provides specialized policies and customer-focused service.
18. CSAA Insurance Group: As part of the AAA network, CSAA offers tailored home insurance solutions with benefits like roadside assistance.
19. Amica Mutual: Renowned for its exceptional customer service, Amica Mutual offers a variety of home insurance options with potential dividends for members.
20. Hippo: Hippo is a new entrant in the market, offering modernized home insurance policies with a tech-forward approach.
In conclusion, these companies represent the top 20 best home insurance companies in the United States, and each offers distinct advantages catering to various homeowner needs. Evaluating the unique offerings and market positions of each provider can assist individuals in making informed decisions about their home insurance coverage.
Comparative Analysis of Coverage Options
When selecting from the top 20 best home insurance companies in the United States, understanding the coverage options each provider offers is essential. Homeowners need to know the different levels of protection available to them. Each of the leading insurers has its unique offerings, which can significantly influence policy selection. This analysis breaks down key aspects such as coverage limits, available endorsements, and common exclusions.
Coverage limits refer to the maximum amount an insurer will pay for a covered loss. These limits can vary widely among the top companies, with some offering higher amounts for structural damage or personal property loss. It is essential for homeowners to review these amounts carefully to ensure they have sufficient coverage to rebuild or replace their valued possessions in case of an unfortunate event.
Endorsements, also known as riders or add-ons, provide additional protection that goes beyond standard policy coverage. Many homeowners looking for comprehensive coverage might consider policies that offer endorsements for items such as high-value personal property, water backup coverage, or identity theft protection. The top 20 best home insurance companies in the United States typically allow policyholders to customize their plans through various endorsements, enhancing security specific to individual needs.
Exclusions are another critical aspect of home insurance policies. Each provider lists specific scenarios and events that are not covered under their standard policies. Understanding these exclusions can help homeowners avoid surprises during the claims process. For example, issues like flood damage or maintenance-related problems may not be included unless specifically addressed in the policy or through an additional endorsement. This careful examination of exclusions can guide homeowners in choosing a plan that adequately protects against potential risks.
In conclusion, evaluating the coverage options available from the top 20 best home insurance companies in the United States allows consumers to make informed decisions. By comparing coverage limits, exploring endorsements, and understanding exclusions, homeowners can select a policy that provides the broadest and most relevant protection for their unique needs.
Customer Service and Claims Processes
Customer service serves as a critical component for the top 20 best home insurance companies in the United States, particularly when it comes to managing the claims process. Effective customer support and a streamlined claims system can significantly influence policyholders’ satisfaction and retention rates. Most leading insurance providers prioritize customer service through various channels, ensuring that assistance is readily available whenever needed.
Many of the top-rated home insurance providers offer extensive online resources, including user-friendly websites and mobile applications designed to facilitate communication and policy management. These platforms allow customers to access vital information regarding their policies, view coverage options, and file claims with ease. Furthermore, companies often provide 24/7 customer support through multiple channels such as phone, email, and live chat, enhancing accessibility and responsiveness to client needs.
The claims process, which is often seen as the most critical interaction between policyholders and their insurers, varies significantly among the top 20 best home insurance companies in the United States. Typically, these companies implement straightforward procedures that guide customers through the necessary steps to file a claim efficiently. Usually, the process begins with a report detailing the extent of the damage, followed by an assessment by an insurance adjuster. Efficiency in claims handling is paramount, and firms strive to process claims quickly to minimize the impact on the policyholder.
Moreover, some of the leading home insurance providers have adopted innovations such as digital claims filing, enabling customers to submit documentation and photos via their websites or apps. This modern approach not only accelerates the processing time but also reduces the complexity traditionally associated with claims. By focusing on customer service and efficient claims processes, these providers maintain their positions in the competitive landscape of the home insurance market.
Cost of Home Insurance: Budgeting Tips
Understanding the costs associated with home insurance is crucial for homeowners aiming to maintain financial stability while safeguarding their assets. The top 20 best home insurance companies in the United States may offer various premium rates influenced by numerous factors, including location, home age, and coverage level. On average, homeowners can expect to pay anywhere between $800 to $2,000 annually for home insurance, depending on their state and specific circumstances.
Geographical location plays a significant role in determining insurance costs. For instance, states prone to natural disasters, such as Florida and California, often have higher premiums compared to states with more stable weather patterns. Understanding these variations can assist homeowners in estimating their insurance needs better. By researching the average rates in their particular state, individuals can create a more accurate budget.
When budgeting for home insurance, it is advisable to review your current policy and consider adjusting coverage levels or deductibles. Higher deductibles can lead to lower premiums, but it’s essential to ensure that the deductible amount remains affordable in case of a claim. Furthermore, homeowners should communicate with multiple insurance providers to compare quotes and coverage options, ensuring that they receive competitive pricing from the top 20 best home insurance companies in the United States.
Another effective strategy for reducing home insurance costs is to take advantage of eligible discounts. Many insurers offer discounts for bundling policies, installing security systems, or having certain safety features within the home. Thus, investigating potential savings can yield significant benefits.
In conclusion, navigating the realm of home insurance can be less daunting with a clear understanding of associated costs, budgeting strategies, and the potential for savings. By leveraging these insights, homeowners can make informed decisions tailored to their financial needs while ensuring comprehensive protection through the top 20 best home insurance companies in the United States.
Common Home Insurance Myths Debunked
Home insurance is often surrounded by various myths and misconceptions that can lead homeowners to make uninformed decisions. Understanding the truth behind these myths is essential to ensure that you are adequately protected and informed about the options available to you. One widely held belief is that home insurance covers all types of disasters. In reality, standard home insurance policies typically exclude certain scenarios, such as earthquakes and floods, which require separate coverage. Homeowners may think they are fully protected without realizing the limitations of their policy.
Another myth is that all home insurance providers offer the same level of coverage. This is not the case. The offerings of the top 20 best home insurance companies in the United States can vary significantly in terms of coverage options, premiums, and customer service. It is crucial for homeowners to shop around and compare different policies to find one that best suits their needs and budget.
Many people also believe that their personal belongings are fully covered under their policy. However, most policies include coverage limits on certain categories of items, such as jewelry, art, and electronics. To protect high-value items, homeowners may need to purchase additional riders or endorsements. Additionally, some homeowners assume that minor issues don’t need to be reported to their insurer. It’s important to inform your insurance company about any damages or incidents, as failing to do so can complicate future claims.
Lastly, there’s a misconception that you must wait until your policy renews to make changes to your coverage. In fact, many insurance companies allow you to adjust your coverage whenever your circumstances change. By debunking these myths, homeowners can navigate the insurance landscape more effectively and make choices that will best protect their properties. Understanding the true nature of these misconceptions empowers you to select amongst the various top 20 best home insurance companies in the United States with confidence.
Conclusion and Recommendations
In concluding our examination of the top 20 best home insurance companies in the United States, it is essential to synthesize the pertinent information gathered throughout this guide. Selecting the right home insurance provider is a critical decision that requires careful contemplation of individual circumstances and preferences. Each of the evaluated companies offers a unique set of features, coverage options, and customer service experiences, making it vital to assess which one aligns best with your particular needs.
When determining the most suitable home insurance provider, several factors merit consideration. First, consider the coverage options available. Each homeowner’s situation is distinct, therefore seeking a provider that offers flexibility in policy structures can lead to more tailored protection. Look for companies that provide additional coverage options, such as flood or earthquake insurance, especially if you reside in areas prone to such risks.
Secondly, evaluating customer service ratings and claims processing reviews is imperative. A company’s reliability during critical moments can significantly impact your experience. Reputable insurers often showcase high marks in customer satisfaction surveys, indicating they are responsive and efficient when it comes to claims handling.
Furthermore, pricing should play a significant role in your decision-making process. Although cost is a vital aspect, it is crucial to balance affordability with the level of coverage provided. Carry out a comprehensive comparison among various quotes from the top 20 best home insurance companies in the United States to ensure you make an informed choice.
It is advisable to review policy terms thoroughly and consult with agents to clarify any uncertainties regarding the coverages offered and potential exclusions. Finally, it might prove beneficial to leverage online resources and tools that provide insights and comparisons, aiding in a more educated buying decision.
Frequently Asked Questions: Top 20 Home Insurance Providers in the United States 2026
1. What are the Top 20 Home Insurance Providers in the United States in 2026?
The leading home insurance providers vary by state, coverage needs, pricing, financial strength, customer service, and policy options. A 2026 list should explain its selection criteria rather than treating one provider as universally best.
2. What does homeowners insurance typically cover?
A standard homeowners policy may cover the dwelling, other structures, personal property, personal liability, and additional living expenses, subject to policy limits, deductibles, exclusions, and conditions.
3. How much does homeowners insurance cost in 2026?
Home insurance premiums vary considerably based on location, property characteristics, coverage limits, deductible, claims history, and local risks. Comparing quotes can help identify available pricing for a particular property.
4. What factors affect home insurance premiums?
Insurers may consider the home’s location, age, construction materials, replacement cost, roof condition, coverage limits, deductible, claims history, security features, and exposure to risks such as wind, hail, wildfire, or hurricanes.
5. Is homeowners insurance required in the United States?
Homeowners insurance is generally not required by federal law. However, mortgage lenders commonly require borrowers to maintain adequate property insurance while a home loan is outstanding.
6. Does homeowners insurance cover flooding?
Standard homeowners insurance typically does not cover flood damage. Homeowners in flood-prone areas may need separate flood insurance or another eligible form of coverage.
7. Does homeowners insurance cover hurricane damage?
Coverage depends on the policy and location. Wind and hurricane-related damage may be subject to specific deductibles or exclusions, while flood damage generally requires separate flood coverage.
8. How can I compare home insurance providers in 2026?
Compare coverage limits, exclusions, deductibles, premiums, discounts, claims services, policy features, financial strength, and availability in your state rather than comparing price alone.
9. What is a homeowners insurance deductible?
A deductible is the amount a policyholder generally pays toward a covered claim before the insurer pays the remaining covered amount, subject to the policy terms.
10. Can I save money by bundling home and auto insurance?
Many insurers offer discounts when customers purchase multiple types of insurance from the same company. Availability and savings vary by insurer and state.
11. What is replacement cost coverage?
Replacement cost coverage generally pays the cost to repair or replace covered property without deducting depreciation, subject to the policy’s terms and coverage limits.
12. What is actual cash value coverage?
Actual cash value generally considers depreciation when determining the amount payable for covered damaged or destroyed property.
13. Does homeowners insurance cover personal belongings?
Many homeowners policies provide personal property coverage for belongings such as furniture, clothing, and electronics, subject to policy limits, exclusions, and deductibles.
14. Does homeowners insurance include liability protection?
Standard homeowners policies commonly include personal liability coverage, which may help cover certain legal and financial obligations arising from covered incidents, subject to policy terms and limits.
15. How can I lower my homeowners insurance premium?
Potential options may include increasing the deductible, qualifying for available discounts, improving home security, maintaining the property, updating certain systems, and comparing quotes from multiple insurers.
16. Can I switch home insurance providers?
Yes, homeowners can generally switch insurers, although timing, mortgage requirements, cancellation procedures, and state-specific rules should be considered before changing policies.
17. What should I check before choosing a home insurance provider?
Review the insurer’s available coverage, exclusions, deductibles, claims process, financial information, customer service reputation, discounts, and availability in your state.
18. Does every home insurance provider operate in every state?
No. Insurance availability, coverage options, pricing, and policy forms can differ by state, and some insurers may not offer homeowners policies in certain areas.
19. Why can home insurance rates differ so much between states?
Insurance costs are influenced by factors such as weather risks, natural disasters, construction costs, property values, claims frequency, state regulations, and local insurance-market conditions.
20. How often should I review my homeowners insurance policy?
Review your policy at least annually and after major changes such as renovations, purchasing expensive belongings, refinancing, moving, or making significant changes to the property.
Read More:

One thought on “Top 20 Home Insurance Providers in the United States 2026”